Insurance vs Cash-Pay Primary Care: What You Actually Get
Weighing insurance vs cash-pay primary care? See what each model actually covers, what it costs, and how to pick the right fit for your health needs.
Alaa Hammond, MSN, APRN, FNP-C, MSN, APRN, FNP-C
September 14, 2026
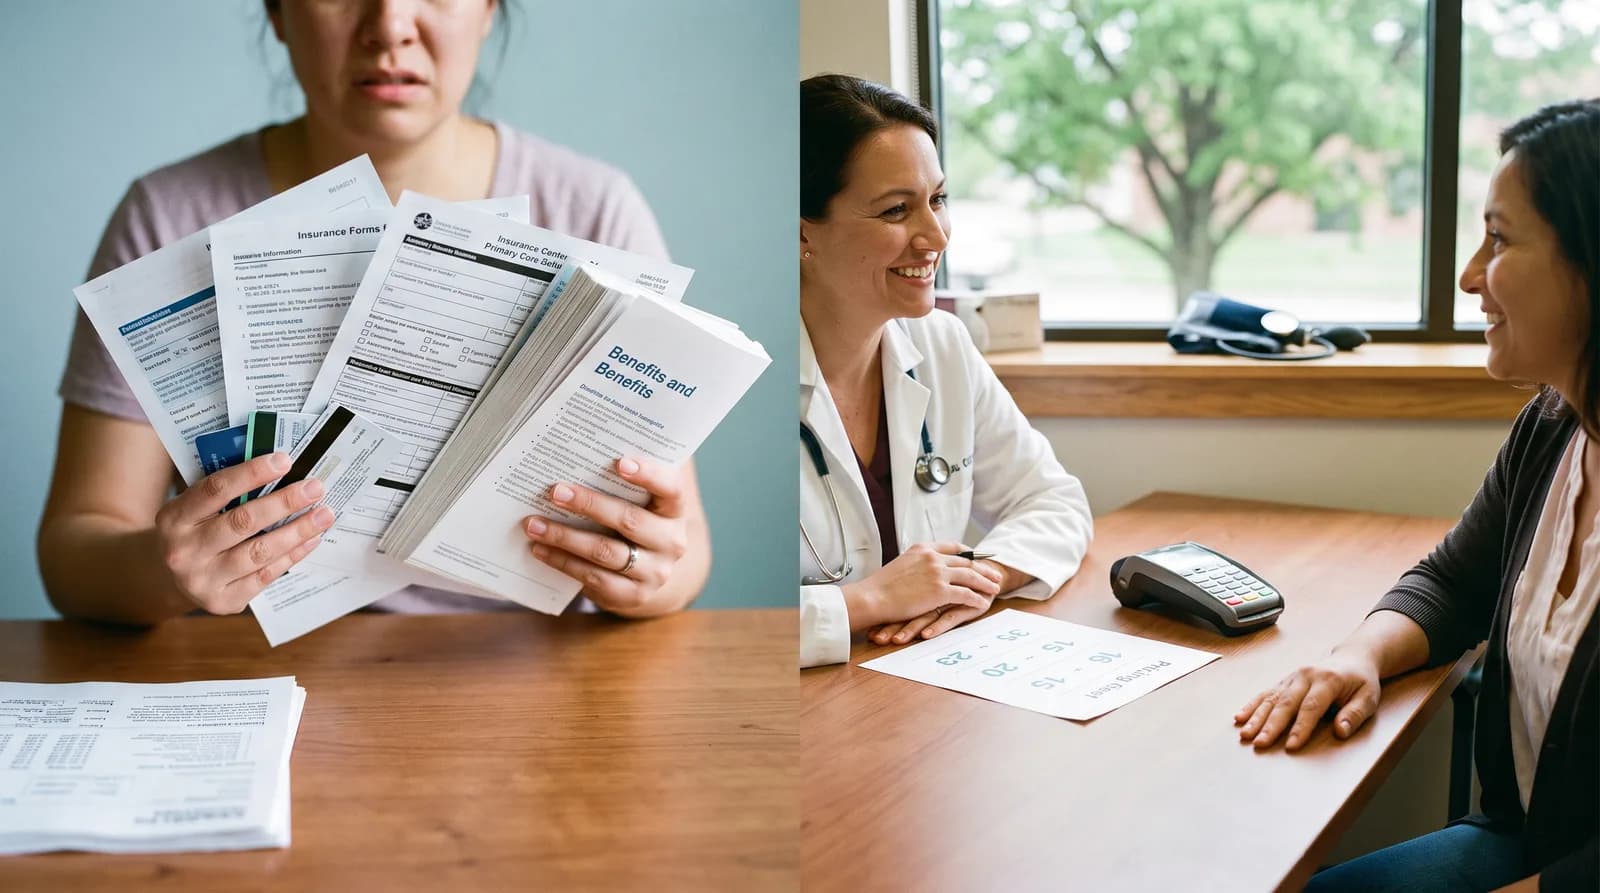
If you are comparing insurance vs cash-pay primary care, the choice usually comes down to two things. What you pay up front, and how much flexibility you want. 6 in 10 U.S. adults live with a chronic condition, according to the CDC, so a steady primary care relationship is worth having either way. Here's what actually changes between the two models.
What Does "Cash-Pay" or "Self-Pay" Primary Care Actually Mean?
Cash-pay, or self-pay, primary care means you pay the clinic directly instead of routing the bill through insurance. There's no claim filed and no network to check. Most self-pay clinics publish a flat rate ahead of time, so you know the cost before you walk in.
This model has grown alongside high-deductible plans, since many patients realized their deductible made an insurance visit cost about the same anyway. It also appeals to the uninsured and anyone who wants faster care without a referral. For a plain-language overview, MedlinePlus is a useful starting point.
- A single, published fee for the visit itself
- No insurance claim or explanation of benefits to decode
- Basic services often bundled into that one price
- Specialty labs or imaging usually billed separately
Before booking, ask what's actually included. A "visit fee" that excludes bloodwork isn't the full picture.
How Does Insurance-Based Primary Care Typically Work?
Insurance-based primary care means your plan pays the practice after you meet your copay, deductible, or coinsurance. Sounds simple. In practice, the process runs through your insurer's rules, not just the clinic's schedule.
That usually means confirming you're in-network and sometimes getting prior authorization before certain tests. Specialist visits often require a referral first. None of this is a bad thing: having a usual source of primary care is linked to better outcomes, according to AHRQ research. In fact, 90% of the nation's annual health care spending goes toward people managing chronic and mental health conditions, per CDC data.
Before your visit, confirm your provider is in-network and what your plan requires for referrals. A quick call avoids a surprise bill.
Not Sure Which Option Fits Your Coverage?
Not sure what your plan covers, or what a self-pay visit would run you? Our front desk can walk you through both.
See Insurance & Pricing Options →What Do You Get With Each Model: Coverage, Time, and Access?
With insurance, you typically get a lower per-visit cost but a shorter appointment window shaped around billing codes. With cash-pay, you get an upfront price and often more time with your provider.
Neither model is universally better. Insurance can absorb the cost of ongoing chronic care, where visits add up over a year. Cash-pay tends to shine for quick, same-day sick visits.
| What You Get | Insurance-Based | Cash-Pay |
|---|---|---|
| Visit length | Often shaped by what's billable that day | Typically more flexible |
| Referral needed | Often, for specialist care | Not typically required |
| Who pays first | Your insurer, after your share | You, directly, at the visit |
How Do Insurance vs Cash-Pay Primary Care Costs Actually Compare?
Costs vary by plan and visit type, but cash-pay usually means one flat rate, while insurance costs depend on your deductible, copay, and coinsurance. A visit that looks less expensive with insurance can cost more once your deductible is factored in.
If you have a low-deductible plan and see your provider often, insurance is usually the better deal. If your deductible is high, cash-pay pricing can end up close to what you'd pay anyway, minus the paperwork. MedlinePlus's consumer guide to choosing care covers this in more depth.
| Factor | Insurance-Based | Cash-Pay |
|---|---|---|
| Pricing | Depends on deductible and copay | One published, upfront rate |
| Scheduling | Can involve eligibility checks | Often same-day or next-day |
| Best for | Frequent visits, chronic care | Occasional visits, fast access |
See What a Visit at Lyva Actually Costs
Book a same-day or telehealth appointment and ask our team to walk you through your insurance or self-pay options.
Book an Appointment →Which Model Fits Your Health Needs and Budget?
Which model fits you depends on how often you see a provider and how much you value speed over savings. Frequent chronic-care visits usually favor insurance. Occasional, fast-turnaround visits often favor cash-pay.
If you saw a provider once or twice last year for a cold or a physical, cash-pay's simplicity might suit you well. If you're managing high blood pressure or another condition needing regular monitoring, insurance usually spreads that cost out more predictably. That matters given the numbers: nearly half of U.S. adults, about 48%, have high blood pressure, and only 1 in 4 have it under control, per the CDC.
- Estimate how many visits you'll realistically need this year
- Check your plan's deductible and what you've already paid toward it
- Decide how much same-day access and flexibility matters to you
Does Lyva Accept Insurance, or Offer Cash-Pay Options Too?
Yes, Lyva Primary Care & Wellness Center accepts most major insurance plans and also offers transparent self-pay pricing for patients without coverage. You don't have to pick a lane before you've scheduled.
Lyva is a nurse-practitioner-led practice in Avondale Estates, Georgia, with telehealth available statewide. Whether you're insured, between plans, or paying cash while you shop for coverage, the intake team can confirm what a visit will cost before you're seen.
If you're not sure which billing path applies to you, ask directly. It's a five-minute call that can save you a confusing bill later.
The real decision between these two paths isn't which model is objectively better. It's which one matches how often you need care and how much you value upfront certainty. Either path works, as long as you know the terms before you're seen, not after.
Ready to Talk Through Your Options?
Book an appointment and our team will confirm your insurance benefits or self-pay pricing so there are no surprises.
Book Appointment →Prefer to talk it through first?
Call (404) 905-6666 →Alaa Hammond, MSN, APRN, FNP-C
MSN, APRN, FNP-C · Lyva Primary Care & Wellness Center
Avondale Estates, GA family nurse practitioner providing whole-person primary and preventive care — including chronic disease management, men's health, and medical weight loss — in person and via telehealth across Georgia.
Frequently Asked Questions
Was this article helpful?
You may also like
Perimenopause Symptoms: What's Normal and When to Test
Perimenopause symptoms vary widely. Learn which changes are normal, which need attention, and when to ask about hormone testing at Lyva Wellness.
How to Get a Same-Day Mental Health Appointment in Atlanta
Need a same-day mental health appointment in Atlanta? Learn what care is available fast, how telehealth helps, and how to get started at Lyva.
8 Tips for Choosing a Primary Care Provider in Metro Atlanta
8 practical tips for choosing a primary care provider in Metro Atlanta, covering insurance, provider type, location, telehealth, and switching records.
Ready to Start Your Health Journey?
Schedule your appointment today and take the first step toward better health. New patients welcome. Most insurance accepted.

Primary Care • Men's Health • Weight Loss Clinic
Phone
+1 (404) 905-6666
Location
Avondale Estates, GA
Hours
Mon-Fri: 8AM - 6PM